When older generations look at young adults struggling to gain financial footing, the lecture is predictable, stop buying expensive coffee, cut back on subscriptions, work harder, put in more hours.
That critique is viewing today’s economy through a rearview mirror that reflects a world that no longer exists.
It remembers an era where an entry-level job or a high school diploma came with a fundamental social contract:
Work an honest 40 hours a week, and your labor bought a stable, dignified life. You could purchase a home, pay off a reliable car, cover health care for a family, and put away savings with a single paycheck.
One partner could manage the home or raise children without the family teetering on the edge of going broke.
Today, that math belongs to an entirely different universe.
The economic exhaustion felt across the country is not a moral failure or a collapse in work ethic. It is the inescapable result of a mathematical breaking point.
The Math: The Death of the Single-Income Baseline
The easiest way to expose the generational divide is to strip away cultural talking points and look at historical real estate against wages.
In 1970, the median American home cost roughly 2.4 times the median annual household income. Decades ago, if you needed to move for work, you found an apartment that matched local wages, paid a modest deposit, and settled in. Visible homelessness was a fraction of what it is today because entry-level wages still covered entry-level shelter.
Today, that price-to-income multiple has exploded to over 5.3 times income nationally and routinely shatters 8x to 12x in major employment hubs. If median home prices had grown at the exact same pace as median wages since 1970, a typical American home today would cost roughly $200,000, not north of $415,000.
Macro Data Breakdown
The 50-Year Housing Affordability Divide
Home-Price-to-Income Multiplier (Years of median income required to buy a median home). Sources: U.S. Census Bureau & FRED.
2.4x income (~$23.4k home / ~$9.8k income)
3.1x income (~$64.6k home / ~$21.0k income)
4.1x income (~$122.9k home / ~$29.9k income)
4.0x income (~$169.0k home / ~$41.9k income)
4.5x income (~$221.8k home / ~$49.2k income)
5.0x income (~$336.9k home / ~$67.5k income)
5.3x+ (~$415k+ home / ~$80.6k income)
When housing detaches from wages, the baseline structure of society fractures.
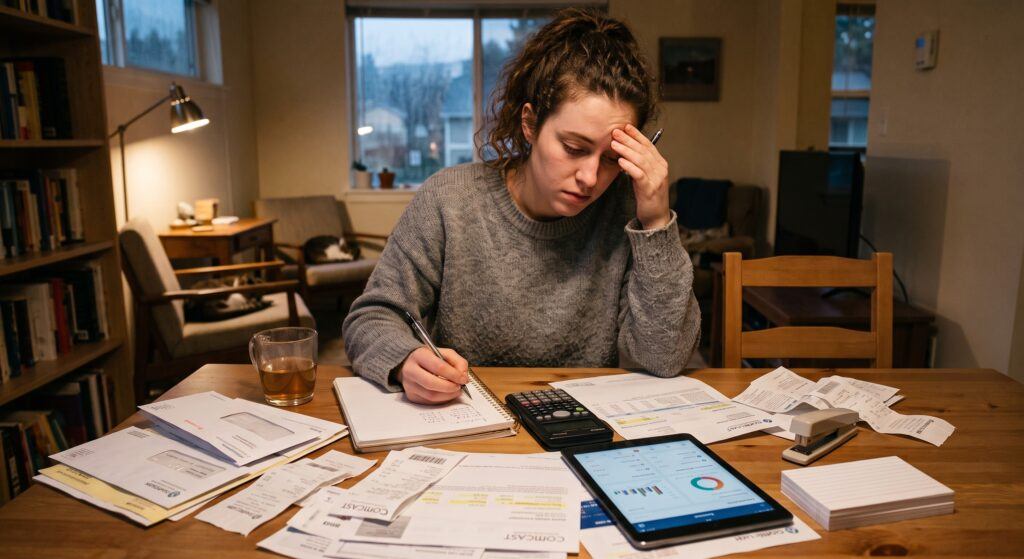
Two full-time incomes are no longer an engine for upward mobility, they have become the bare minimum survival threshold just to service rent, groceries, and basic debt.
The “Silent Squeeze”: Death by a Thousand Utility Hikes
Washington and Wall Street love to point to selective metrics to claim that “inflation is cooling.” But everyday households know that a slowing rate of inflation does not mean prices rolled back.
It simply means the rate of increase stabilized after your household budget was already jacked up another notch.
It is death by a thousand silent paper cuts:
- The Escrow Shock: Millions bought homes believing a 30-year fixed mortgage meant predictable housing costs forever. But property taxes and skyrocketing home insurance premiums have triggered massive escrow shortages, quietly driving monthly payments up by $200 or $300 a month.
- The Monopolistic Creep: You cannot shop around for your municipal water provider, trash hauler, or regional energy grid. Trash goes up $10 a month, phone plans climb $15, auto insurance tacks on another $10 to $20, water bills jump double digits.
- The Desperate Coping Mechanisms: Families aren’t cutting back on luxuries, they are turning off central appliances, living under battery-powered tap lights to lower kilowatt usage, and watching $300 to $400 in net monthly cash evaporate before buying a single carton of eggs.
When non-negotiable household overhead climbs by thousands of dollars a year while salaries stay flat, cutting out an iced coffee doesn’t balance the ledger.
The Architecture of the Triple-Hustle Economy
When two full-time paychecks can no longer absorb routine cost increases, workers are forced into the Triple-Hustle Economy.
A 40-hour workweek becomes merely the daytime baseline. Evenings are spent driving rideshares or delivering groceries, lunch breaks are spent answering digital micro-tasks, and weekends are consumed by reselling items or picking up temporary shifts.
Corporate marketing and tech platforms sell this dynamic as “freedom,” “flexibility,” and “micro-entrepreneurship.” But strip away the PR gloss, and it is a system engineered to offload corporate risk:
- No Safety Net: Independent contractor status strips away employer-paid health coverage, retirement matching, sick leave, and workers’ compensation.
- Depreciating Personal Assets: Workers burn their own fuel, destroy their personal vehicles’ brake pads and tires, and absorb rapid depreciation just to patch a gap on a utility bill often jeopardizing the very car they rely on to reach their primary job.
- Algorithmic Wage Suppression: Workers don’t negotiate pay; they navigate black-box algorithms that squeeze base payouts down to the bare minimum required to keep desperate couriers on the road.
We have built an economic baseline where working full-time is no longer enough to guarantee solvency and where survival itself requires monetizing every waking hour.
Up Next: Part 2 – The Tipping Subsidy & The Safety Deficit
The natural byproduct of an economy where base wages fail is the modern tipping crisis.
Point-of-sale screens now swivel across retail counters and drive-throughs demanding 20% to 30% tips, using consumer guilt to crowdfund payroll that corporations refuse to write. Meanwhile, front-line delivery workers are forced onto isolated porches and into hostile neighborhoods alone, facing aggressive dogs and rating cliffs just to make rent.
Continue reading Part 2: The Tipping Trap: How Corporate Apps Subsidize Wages and Outsource Danger, where we break down the point-of-sale screen swivel, gig delivery safety hazards, and corporate balance sheets.
Join the Discussion
Are you or someone in your family working a second or third shift just to patch inflation and utility hikes? How does your monthly budget compare to where things stood five or ten years ago?
Drop your thoughts, experiences, and local utility/rent numbers in the comments below.